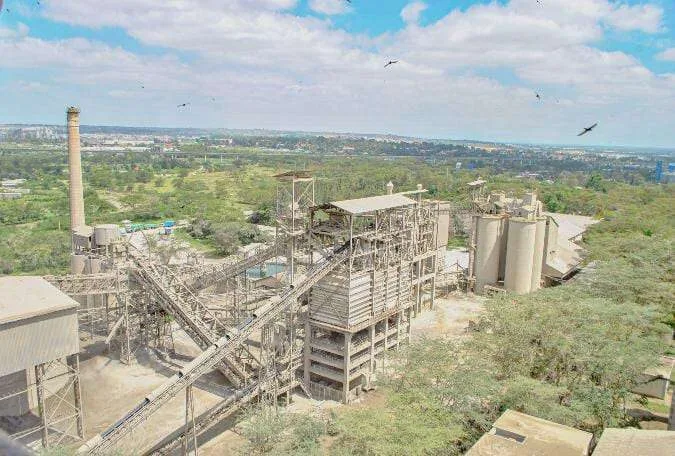
East African Portland Cement Company (EAPCC) recorded profit after tax of KSh1.58 billion for the financial year ended June 2026, a fall of 68.6 per cent from KSh5.02 billion in the prior year.
Revenue rose 28.1 per cent to KSh9.07 billion, helped by a 30 per cent increase in cement output and a 29 per cent rise in sales volumes, yet profit before tax dropped 66.1 per cent to KSh1.88 billion and earnings per share fell to KSh17.55 from KSh55.82.
The company said the sharp reduction in fair-value gains on investment properties, which fell 50.9 per cent to KSh1.91 billion from KSh3.90 billion, cut non-operating income, while operating results swung to a loss of KSh52.4 million after a profit of KSh1.64 billion a year earlier.
Gross profit improved 15.5 per cent to KSh1.20 billion, but the gross margin narrowed by 1.1 percentage points as higher energy costs and logistics expenses lifted production and distribution costs; EAPCC attributed the tougher operating environment to elevated inflation and supply-chain disruptions linked to geopolitical tensions.
Net cash used in operating activities amounted to KSh321.3 million, compared with an inflow of KSh242.7 million in the previous year, and cash and cash equivalents declined 5.2 per cent to KSh648.6 million, while total assets grew 3.3 per cent to KSh51.96 billion.
The board chose not to recommend a dividend, opting to preserve cash for capacity-expansion projects as the firm seeks to capture expected growth in cement demand. EAPCC said it will aim to restore operating profitability through better plant efficiencies, optimal sourcing and expansion of capacity to benefit infrastructure projects anticipated to sustain construction activity in the medium term. “The domestic cement market rebounded during the financial year resulting in higher product uptake although competition and price pressure persisted,” the company said in its financial results.