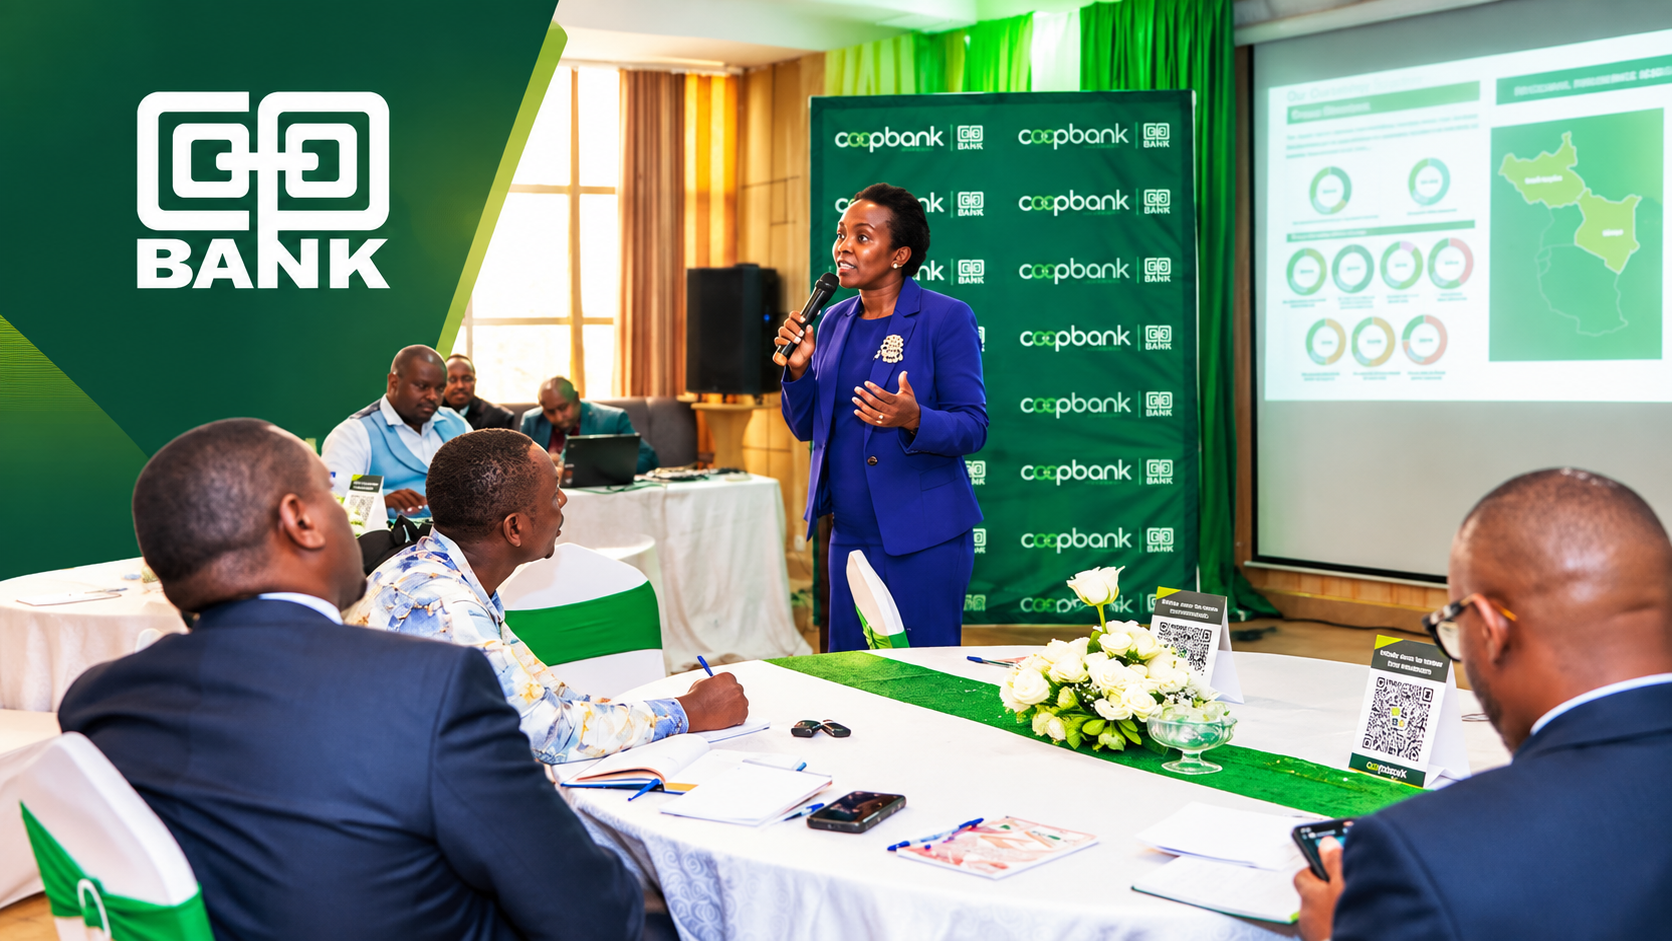
Co op Bank Kenya is engaging micro, small and medium enterprises in the Central Region through direct business discussions. The conversations focus on the practical realities entrepreneurs encounter while running their businesses. They also give customers an opportunity to raise questions about financing and trade.
The engagement forms part of the bank’s broader interaction with businesses and entrepreneurs across Kenya. Co op Bank says it regularly meets customers to understand their business journeys and financial requirements. The approach places direct customer feedback at the centre of discussions about banking services.
For MSMEs, such conversations provide a channel to discuss operational challenges directly with a financial institution. Business owners can explain the conditions under which they manage their enterprises. They can also identify areas where financial products and services need to respond to their circumstances.
The Central Region discussions have covered everyday experiences associated with running a business. Co op Bank has also shared practical business tips with participating entrepreneurs. The discussions therefore extend beyond lending to address broader questions that affect business management.
Financing remains one of the areas addressed during the engagement with MSME customers. Access to suitable financial services can influence how enterprises manage their working capital and business activities. The source does not provide figures on loans discussed, applications received, or financing ultimately extended to participants.
Trade is another area covered in the conversations between the bank and business owners. For enterprises, trade activity can create financial requirements that differ according to their operations and customer base. The bank’s engagement gives entrepreneurs an opportunity to raise questions about those requirements and seek relevant guidance.
The discussions also offer the bank a direct view of how customers experience its services. Feedback from business owners can provide useful information about the challenges encountered during ordinary commercial activity. Co op Bank says these interactions help it develop services that respond to individual customer needs.
The approach is relevant to a business sector that spans enterprises at different stages of development. An emerging enterprise may require different financial services from an established trading business. Direct engagement allows those differences to form part of conversations between customers and the bank.
Co op Bank’s Central Region engagement also demonstrates the role of customer interaction in shaping financial services. The bank has positioned business conversations as part of its support for enterprise development. Its stated objective is to understand customer needs and align services with those requirements.
The available information does not establish the number of MSMEs involved in the discussions or the financial value generated. It also does not provide measurable results from the engagement or identify specific new products arising from the conversations.
The evidence therefore supports a conclusion about sustained customer engagement rather than a quantified assessment of its commercial impact.