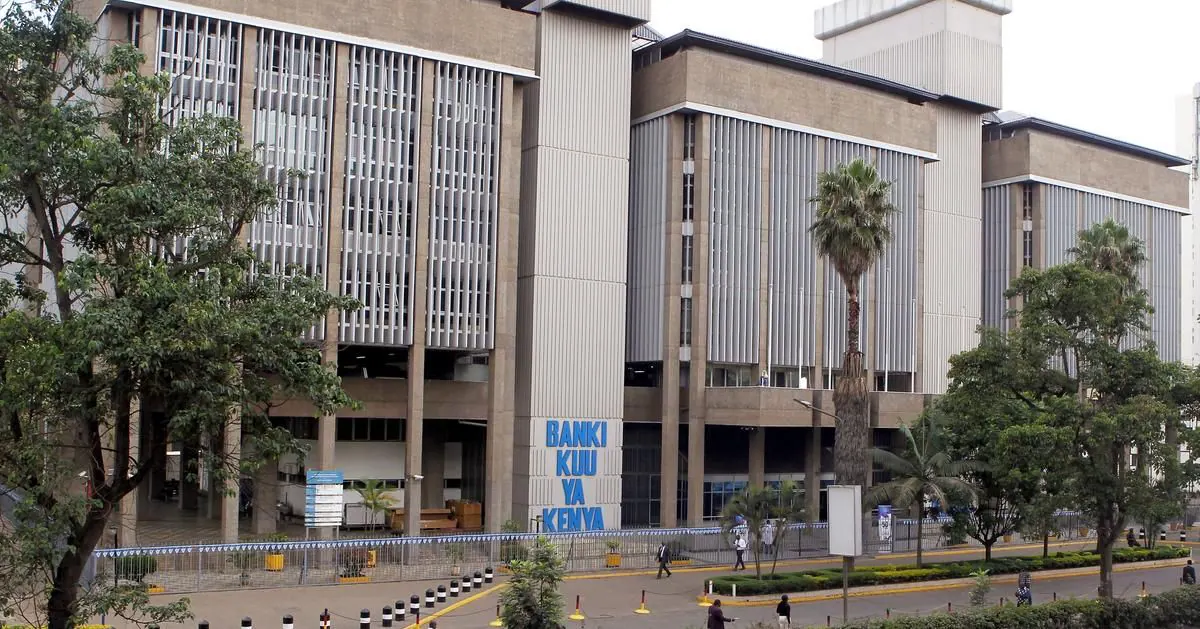
Kenyan lenders have fallen out of Africa’s top-10 fastest-growing banks in the latest The Banker ranking, after the Kenyan shilling stopped appreciating against the US dollar.
The new list shows no Kenyan bank among the continent’s ten highest movers, whereas the previous edition featured KCB Group, Co-operative Bank, Equity Group and NCBA.
Most Kenyan lenders still posted rises in Tier 1 capital, assets and pre-tax profit, with Standard Chartered Bank Kenya the only exception, recording a decline in its capital position.
Over an extended period the shilling traded in a tight band of roughly KSh129.00 to KSh129.92 per dollar, following a sharp appreciation in 2024 that had boosted the dollar-denominated size of Kenyan banks.
The Banker explained that the loss of this currency-driven boost allowed banks in markets where local currencies strengthened or where capital was raised to move ahead in the ranking.
It noted that exchange-rate effects can alter comparative size even when underlying shilling-denominated balances remain unchanged, and that a lower ranking does not automatically signal weaker capital, lending or profitability.
Kenyan institutions also lost representation among Africa’s five banks with the highest return on assets.
KCB Group slipped to 15th place in the African ranking and Equity Group to 17th, although globally KCB improved to 542nd from 590th and Equity to 573rd from 590th.
KCB reported first-half 2026 total assets of KSh2.299 trillion, up 16.8 per cent, deposits of KSh1.711 trillion, up 15.1 per cent, gross loans up 14.2 per cent and a reduction in gross non-performing loans of KSh17.3 billion.
Equity Group posted first-half profit after tax of KSh45.5 billion, deposits of KSh1.59 trillion, up 21 per cent, total assets of KSh2.16 trillion and net loans up 19 per cent.
Nine of the eleven Nairobi Securities Exchange-listed banks that released results recorded a combined net profit of KSh144.9 billion, a 16.9 per cent increase from KSh124 billion a year earlier, helped by lower funding costs and better asset quality.
In Nigeria, banks rose in the continental comparison after the naira’s sharp devaluation from 2023 and the Central Bank of Nigeria’s March 2024 increase in minimum capital requirements, which forced banks to raise equity, alter licences or merge.
The Banker reported that Tier 1 capital across the Nigerian sector grew by 36 per cent in dollar terms, with Stanbic IBTC Holdings, Standard Chartered Nigeria and Access Holdings posting the largest gains.
Access Bank acquired National Bank of Kenya from KCB Group and Zenith Bank bought Paramount Bank, expanding Nigerian footprints in Kenya.
Fourteen of Africa’s top-25 lenders maintain a presence in Kenya, underscoring the market’s attractiveness to regional and international banks.
South African groups are prominent, with Standard Bank Group’s Stanbic, Absa (ranked third) and Nedbank (ranked fifth) among the leading institutions; Nedbank completed a 66 per cent acquisition of NCBA in October 2026.
Kenyan banks have entered markets such as the Democratic Republic of Congo and South Sudan, but face currency, political and operational risks that complicate building larger pan-African banking groups.
Moody’s indicated that Kenyan banks held government securities worth 1.7 times their equity at the end of December 2025, linking part of their balance sheets to state creditworthiness.
“The dramatic dollar gains the Kenyan banking sector enjoyed in 2024 thanks to the strengthening of the shilling were not repeated last year, with the currency largely unchanged against the greenback due to the central bank’s ‘crawling peg’ strategy,” said The Banker.
“The stability of the shilling saw Kenyan lenders slip down the rankings at the expense of other lenders in countries where currencies strengthened against the dollar, even as all but one (Standard Chartered Bank Kenya, whose capital position slipped) recorded increases in Tier 1 capital, assets and pre-tax profits,” it added.
“Following the sharp devaluation of the naira from 2023, the Central Bank of Nigeria in March 2024 significantly increased paid-in capital requirements for commercial, merchant and non-interest banks in 2024, obliging banks to change their licence status, inject additional equity or pursue mergers,” said The Banker.
“Widespread equity raising by lenders saw Tier 1 capital increase by 36 per cent in dollar terms during the year, with Stanbic IBTC Holdings, Standard Chartered Nigeria and Access Holding posting the largest overall gains,” it added.