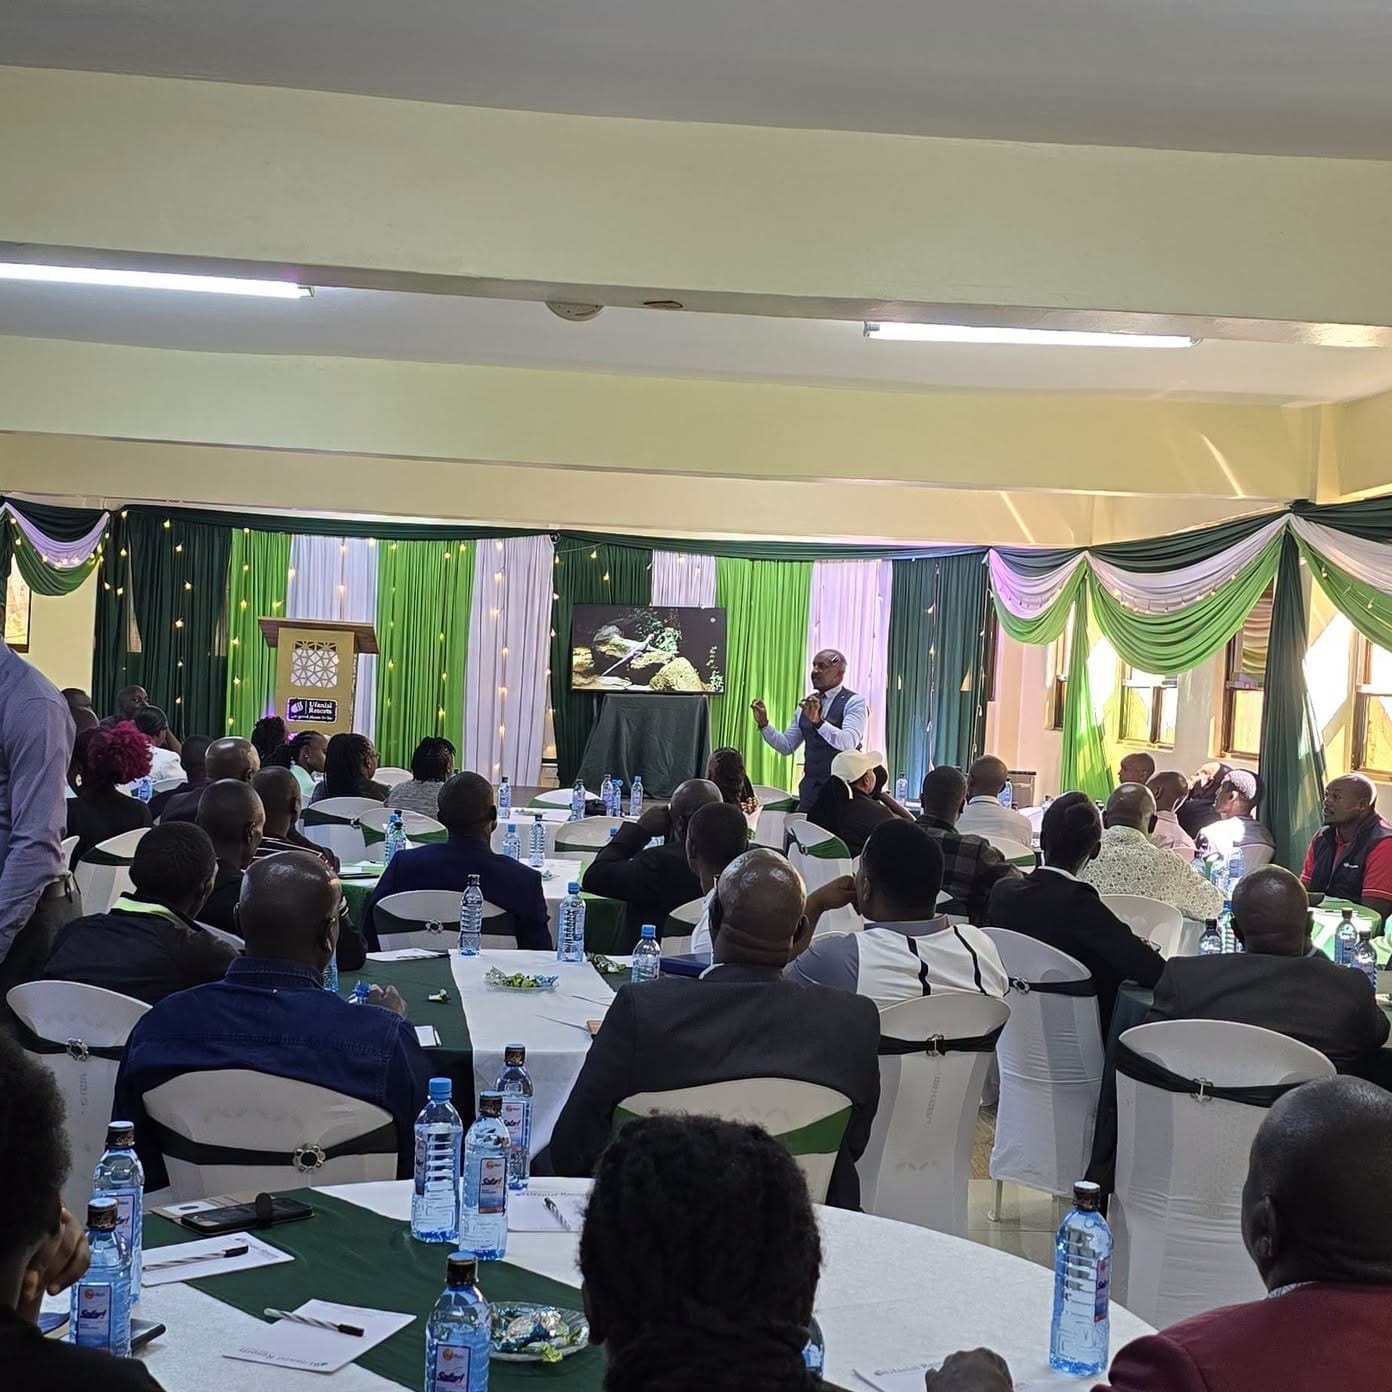
Co operative Bank of Kenya has extended its engagement with micro, small and medium enterprises across western Kenya. The outreach covered Migori and Kisii, where the bank met entrepreneurs to discuss business needs and growth opportunities.
The initiative focused on strengthening customer relationships through direct conversations with local business owners. Regional Head Paul Chianda led the bank’s team during the engagements. Discussions centred on exchanging ideas, understanding business challenges and exploring ways to support enterprise development.
The visits reflect the importance of MSMEs to Kenya’s regional economies and local employment. Smaller enterprises support household incomes, commercial activity and supply chains across different sectors. Their performance can influence demand for goods and services within towns and surrounding communities.
Businesses also operate under different financial conditions, depending on their industries, size and revenue patterns. Many require working capital to purchase stock, pay suppliers and manage routine operating expenses. Reliable payment services and suitable financial products can help them maintain operations and plan for expansion.
Direct engagement allows banks to learn more about these requirements from the businesses themselves. Conversations can reveal gaps between available banking services and the practical needs of entrepreneurs. Such feedback can inform service improvements and help lenders build stronger, longer lasting customer relationships.
Co operative Bank said the outreach offered opportunities to exchange insights and explore business growth prospects. The bank also recognised the resilience and entrepreneurial drive demonstrated by customers across western Kenya.
It expressed its commitment to supporting enterprises pursuing innovation, employment creation and regional economic development.
The outreach also comes amid competition among lenders seeking to serve Kenya’s growing small business market. Entrepreneurs often compare banks through transaction costs, credit terms, digital services and customer support.
Financial institutions that respond to these priorities may strengthen customer retention and identify new business opportunities.
The bank did not disclose how many businesses participated or whether the visits generated financing commitments. No new products, agreements or measurable economic outcomes were announced following the engagements. The immediate commercial impact therefore remains unclear, pending evidence of practical outcomes.
For entrepreneurs in Migori and Kisii, continued dialogue could improve communication with financial service providers. The longer term value will depend on whether feedback translates into accessible products and responsive support.
Effective banking partnerships could help businesses strengthen resilience, sustain employment and contribute to regional economic growth.